
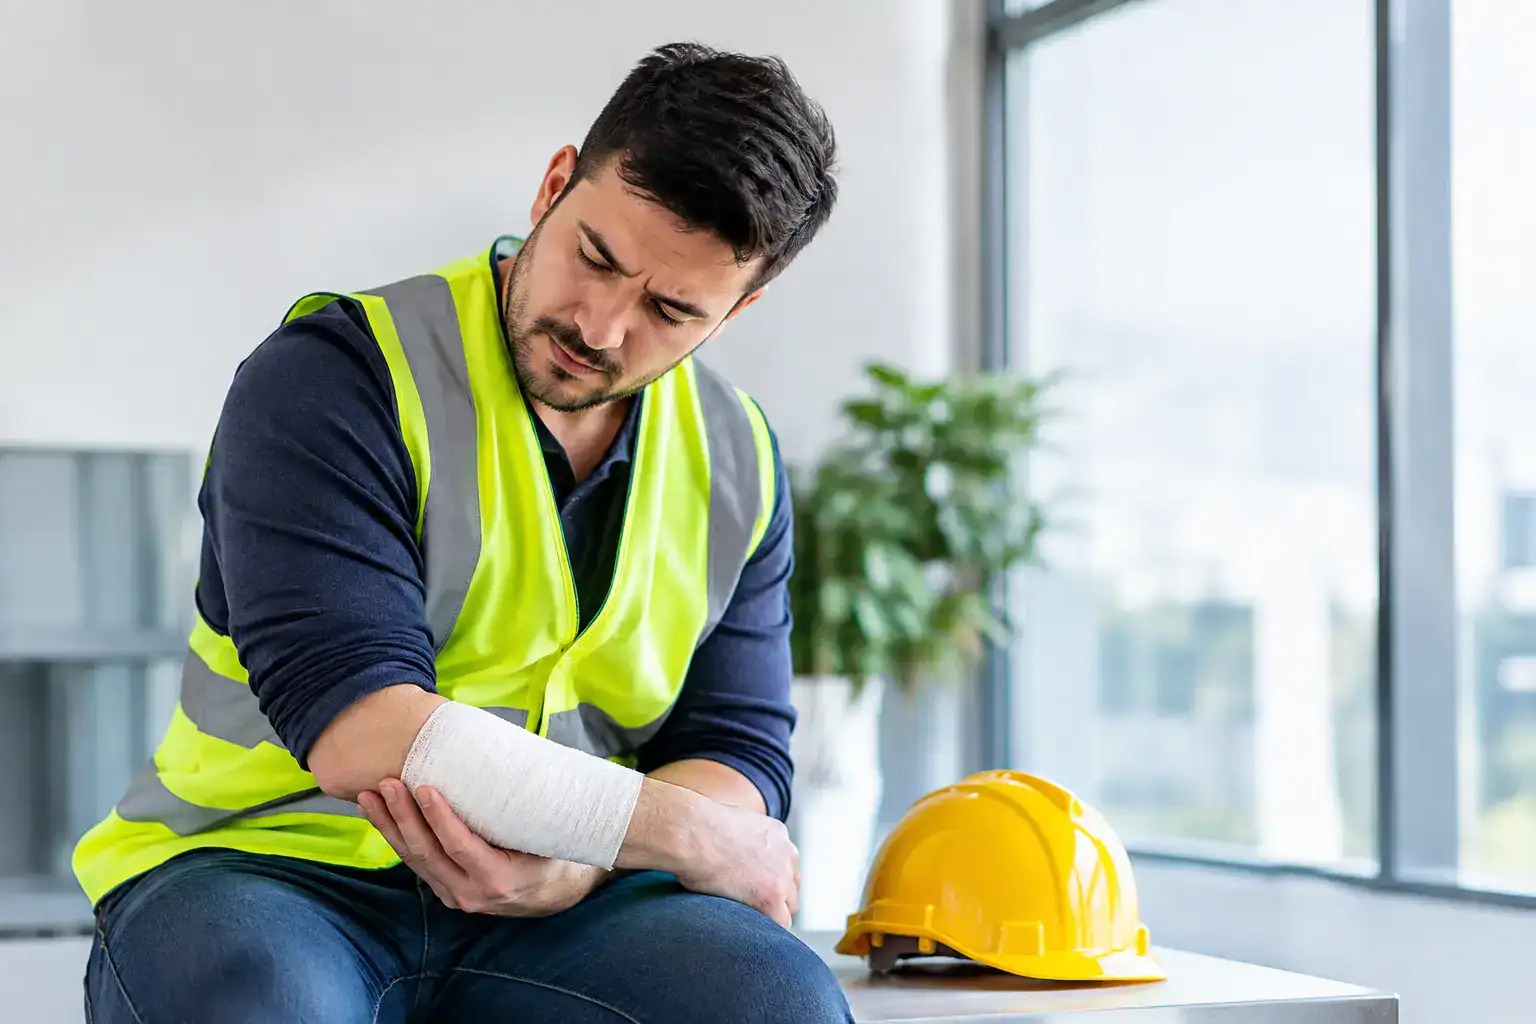
A new hire can trigger an insurance requirement before their first shift begins. The question, “when is workers compensation required,” usually has a state-specific answer, but waiting until someone is hurt is never the right time to find out. A work injury can create medical bills, lost-wage obligations, legal costs, and penalties for operating without required coverage.
For most U.S. small businesses, workers’ compensation becomes mandatory when the business has employees. The details – including the number of employees that triggers the rule, whether part-time staff count, and which owners may opt out – depend on the state where work is performed.
When Is Workers Compensation Required?
Workers’ compensation is generally required when an employer has one or more employees and operates in a state that mandates coverage. Nearly every state has a workers’ compensation law, but the thresholds and exemptions are not identical.
Some states require coverage as soon as you hire your first employee. Others allow a limited exception for very small employers, certain agricultural operations, domestic workers, or casual labor. Construction businesses often face stricter rules because job-site injuries can be severe and frequent. In many states, a contractor must carry workers’ compensation even with a very small crew.
The key distinction is whether a person is legally your employee, not whether you call them a helper, temporary worker, or 1099 contractor. If you control how, when, and where someone performs their work, supply their tools, and treat them as part of your ongoing operation, state regulators may determine that they are an employee. Misclassifying workers can lead to unpaid premiums, fines, stop-work orders, and liability for an injury claim.
Why State Rules Matter More Than a General Rule
Workers’ compensation is regulated primarily at the state level. There is no single federal requirement that applies to every private employer. That means a business owner in Texas may have different obligations than an owner with the same number of employees in California, New York, or Florida.
Most states require employers to buy coverage through a private insurance carrier or a state fund. A few permit qualified larger businesses to self-insure, but that option requires substantial financial resources and administrative controls. For the typical small business, purchasing a policy is the practical route.
Texas is a notable exception because many private employers can choose whether to carry workers’ compensation. Even there, going without coverage can expose a business to lawsuits from injured employees and may limit the defenses available to the employer. Clients, general contractors, and government entities may also require proof of coverage regardless of whether state law does.
If you operate across state lines, do not assume your policy automatically meets every requirement. A landscaping company based in one state, for example, may need to address workers who regularly perform jobs in a neighboring state. Tell your insurance agent where employees live and work, including temporary projects, so the policy can be structured correctly.
Who Counts as an Employee?
Full-time employees are the obvious example, but workers’ compensation obligations can extend further. Depending on the state and the work arrangement, your employee count may include part-time staff, seasonal employees, temporary workers, minors, family members on payroll, and remote employees.
A restaurant that adds weekend servers, a retail shop hiring holiday help, or a contractor bringing on a laborer for a short project may cross the state’s threshold quickly. Payroll size and job duties also affect premium costs, so report each worker accurately from the start.
Business owners, corporate officers, partners, and LLC members are handled differently from state to state. In some cases, they are automatically covered. In others, they can elect coverage or file a formal exclusion. An owner exclusion may lower premium, but it also means that person may have no workers’ compensation benefits after a job-related injury. For hands-on owners, that trade-off deserves careful consideration.
Independent contractors require special attention. A legitimate independent contractor generally controls their own work, carries their own business expenses, and may work for multiple clients. But a signed 1099 form does not settle the issue. If a contractor is injured and is later deemed your employee, your business could be responsible for the claim and noncompliance penalties.
Contract Requirements Can Make Coverage Necessary
Even when a narrow state exemption applies, workers’ compensation may still be necessary to win work. General contractors frequently require subcontractors to provide a Certificate of Insurance before entering a job site. Property managers, municipalities, staffing platforms, and commercial clients may do the same.
This requirement protects the hiring party from being drawn into an injury claim involving your workers. Without a certificate, you may be denied access to the project, have payments withheld, or be charged for coverage through the contractor’s policy. That charge can be more expensive and offer less control than securing your own policy.
For a subcontractor, carrying workers’ compensation can also support credibility. It shows clients that your company has planned for employee injuries rather than shifting the financial risk onto the project owner.
What Workers’ Compensation Typically Pays For
Workers’ compensation is designed for employees who are injured or become ill because of their work. A policy commonly pays for reasonable medical treatment, a portion of lost wages while an employee cannot work, rehabilitation expenses, and death benefits when a fatal workplace injury occurs.
It also usually includes employers liability coverage. This can help defend the business if an employee or family member brings a lawsuit alleging that the employer’s negligence caused an injury. Policy terms, limits, and state benefits rules vary, so coverage should be reviewed against your operation.
Consider a flooring contractor whose employee injures a knee while carrying materials up stairs. The claim may involve emergency treatment, surgery, physical therapy, and weeks away from work. Without workers’ compensation, the contractor could be paying those costs directly while also facing a claim for lost income or alleged unsafe conditions.
Workers’ compensation is not the same as general liability insurance. General liability is built to address third-party bodily injury, property damage, and related legal defense. If a customer slips in your store, general liability may respond. If your employee slips while stocking inventory, workers’ compensation is the coverage designed for that loss. Many businesses need both because employees and third parties create different exposures.
How to Stay Compliant Before Hiring
The best time to address workers’ compensation is before payroll begins. Start by confirming the requirements in every state where employees will work. Then classify each worker correctly, estimate annual payroll, and identify job duties accurately. A clerical employee and a roofer may have very different premium classifications because their injury risks are not comparable.
Keep payroll records current throughout the policy term. If you add employees, expand into higher-risk work, or take projects in another state, notify your carrier promptly. Workers’ compensation policies are often audited after the policy period, and inaccurate payroll or classifications can result in an additional premium bill.
You should also maintain a clear workplace safety process. Safety training, documented procedures, proper protective equipment, and prompt injury reporting can reduce claim severity. They may also help protect your workforce, which is the most valuable result.
When you need proof of coverage quickly, ask for a Certificate of Insurance that lists the required workers’ compensation details. GeneralLiabilityInsure.com can help small business owners compare policy options, secure coverage, and obtain documentation needed for a contract or job.
A workers’ compensation policy is not just a box to check before a project starts. It is a practical way to protect the people doing the work, preserve business cash flow after an injury, and keep a growing company ready for its next opportunity.
Related General Liability Insurance articles:
Free Business Insurance Quote
Want to speed up your quote? Call us at 855-767-7828