
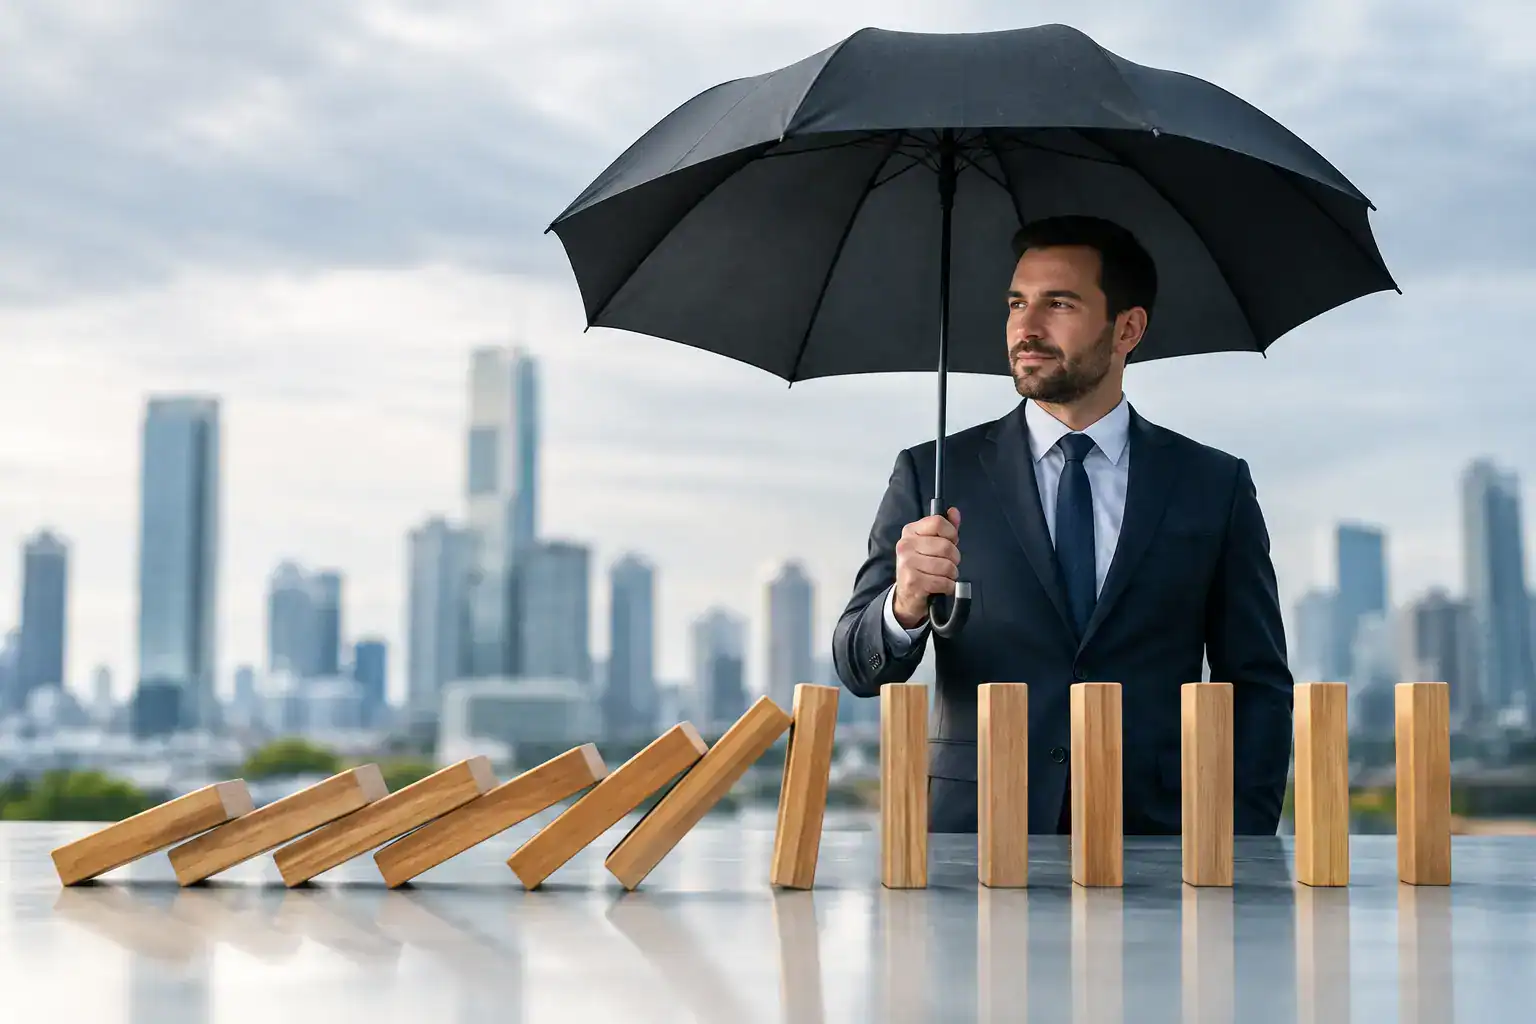
A single serious claim can cost more than the liability limit printed on your policy. That is where business risks requiring umbrella coverage become a practical concern, not just an insurance add-on. If a lawsuit, injury, or major property damage claim exceeds the limits of your underlying coverage, the remaining costs may come from your business assets, future revenue, or personal assets in some business structures.
Commercial umbrella insurance provides additional liability limits above certain underlying policies, often including general liability, commercial auto, and employers liability. It is designed for high-dollar losses, not everyday small claims. For a growing business, the right umbrella limit can help protect the progress you have worked hard to build.
What Commercial Umbrella Coverage Does
An umbrella policy adds another layer of liability protection after the limit of an underlying policy has been exhausted. For example, suppose your general liability policy has a $1 million per-occurrence limit and your business is found liable for $1.8 million in covered damages and legal costs. An umbrella policy may pay the amount above the $1 million primary limit, subject to its own terms and limits.
Umbrella coverage does not replace general liability, commercial auto, or workers’ compensation. It works with qualifying underlying policies. You still need to maintain the required primary coverage and limits, known as the retained limits, before the umbrella layer applies.
This distinction matters. A policy with a high umbrella limit may offer little help if the underlying claim is excluded. It also may require higher limits on your auto or general liability policy than you carry today. Reviewing the entire insurance package is more useful than choosing an umbrella limit in isolation.
Business Risks Requiring Umbrella Coverage Most Often
Not every small business needs the same amount of excess liability protection. The strongest case for umbrella coverage is usually a business with a realistic path to a large third-party claim, meaningful assets to protect, or contract requirements that call for higher limits.
Customer Injuries at Your Location or Job Site
Retail stores, restaurants, salons, gyms, offices, and other businesses that welcome customers face slip-and-fall and premises liability claims. Contractors can also face injury allegations at active job sites. A wet floor, loose handrail, falling material, or poorly marked hazard can result in extensive medical bills, lost wages, and legal expenses.
General liability is the first line of protection for covered bodily injury claims. But severe injuries can create damages far above a standard $1 million limit, particularly when a claimant needs ongoing care or cannot return to work. An umbrella policy gives businesses with regular foot traffic or hazardous operations more room above that primary limit.
Large Property Damage Claims
Property damage is not always limited to a broken window or minor repair. A plumbing contractor may cause a major water loss in a commercial building. An electrician could be blamed for a fire. A cleaning company may damage expensive equipment, inventory, or tenant improvements at a client location.
The value of the affected property, business interruption losses, and legal defense can drive claim costs upward quickly. Businesses that work in high-value homes, medical facilities, office buildings, warehouses, or multi-tenant properties should look closely at whether their general liability limit matches the size of the damage they could cause.
Serious Commercial Auto Accidents
A company vehicle can create one of the clearest reasons to consider umbrella insurance. A severe accident involving injuries to multiple people, a pedestrian, or a high-value vehicle can exceed a commercial auto policy’s liability limit. The exposure increases when employees drive frequently, travel long distances, carry tools or materials, or operate larger vehicles.
Even businesses that use personal vehicles for deliveries, sales calls, or service appointments should review this risk. A commercial auto policy, hired and non-owned auto coverage, and an umbrella policy may need to work together. The appropriate structure depends on who owns the vehicles, who drives them, and how they are used.
Contracts That Require Higher Liability Limits
Landlords, general contractors, government entities, larger customers, and property managers often require liability limits beyond a basic policy. A contract may call for $2 million, $5 million, or more in coverage. Rather than purchasing unusually high limits on every underlying policy, a commercial umbrella can be a cost-effective way to meet the total requirement.
Read the insurance section of the contract carefully. It may specify the required underlying limits, umbrella limits, additional insured status, waiver of subrogation, or other endorsements. A certificate of insurance confirms coverage information, but it does not change your policy. Make sure the policy itself meets the contract before work begins.
Operations With High Public Exposure
Some businesses interact with the public at a scale that changes their liability profile. Event companies, security firms, transportation businesses, contractors, property owners, and companies serving large crowds can face claims involving multiple injured parties. The same is true for businesses that perform work at schools, hospitals, airports, public venues, or busy commercial properties.
The question is not whether a claim is likely every day. It is whether one bad event could produce damages your standard liability limits cannot absorb. If the answer is yes, additional umbrella limits deserve consideration.
Growing Assets and Revenue
As a business grows, its exposure often grows with it. More employees, vehicles, locations, contracts, customers, equipment, and revenue can create more opportunities for a costly loss. At the same time, the business has more assets worth protecting.
An umbrella policy can make sense even for a business with a good claims record. Past losses help insurers evaluate risk, but they do not guarantee the size of the next claim. Higher limits are often about protecting the future income and assets that a successful business has created.
When an Umbrella Policy May Not Be the First Priority
Umbrella coverage is valuable, but it is not a substitute for gaps in basic coverage. A new consultant with no employees, no company vehicle, no physical location, and limited client-facing activity may need professional liability coverage more urgently than an umbrella policy. A business handling payment information or sensitive customer records may need cyber liability protection before adding higher general liability limits.
Likewise, umbrella insurance generally does not cover professional mistakes, employee injuries, property your business owns, intentional acts, or most cyber events unless a policy specifically states otherwise. Those exposures need their own policies or endorsements. The right decision depends on your industry, contracts, operations, assets, and underlying insurance limits.
How Much Umbrella Coverage Should a Business Carry?
Many small businesses begin by considering a $1 million umbrella limit, while businesses with larger contracts, public-facing operations, multiple vehicles, or significant assets may need $2 million, $5 million, or more. There is no universal number that fits every company.
Start with the limits required by contracts and then consider your worst credible loss. Ask what could happen if a vehicle accident caused life-altering injuries, a job-site incident injured several people, or your work damaged an expensive property. Then review the limits on your general liability, commercial auto, and employers liability policies to see where an umbrella layer can apply.
Price is also part of the decision. Umbrella coverage can be an efficient way to add substantial liability limits, but the premium depends on your industry, claims history, revenue, payroll, vehicles, locations, and underlying policies. A quote review can show whether increasing a primary limit, adding an umbrella, or doing both is the better fit.
Get Coverage That Matches Your Actual Exposure
Do not wait for a large contract or a serious claim to find out your limits are too low. Gather your current policy declarations, vehicle details, payroll information, and any client or landlord insurance requirements. With those details, you can compare umbrella options alongside the liability policies that support them.
A fast quote can help you weigh affordable limits against the risks your business takes every time employees drive, customers visit, or work begins at a client property. Protecting your next project, vehicle trip, or customer interaction starts with knowing how much liability protection your business can truly rely on.
Related General Liability Insurance articles:
Free Business Insurance Quote
Want to speed up your quote? Call us at 855-767-7828