
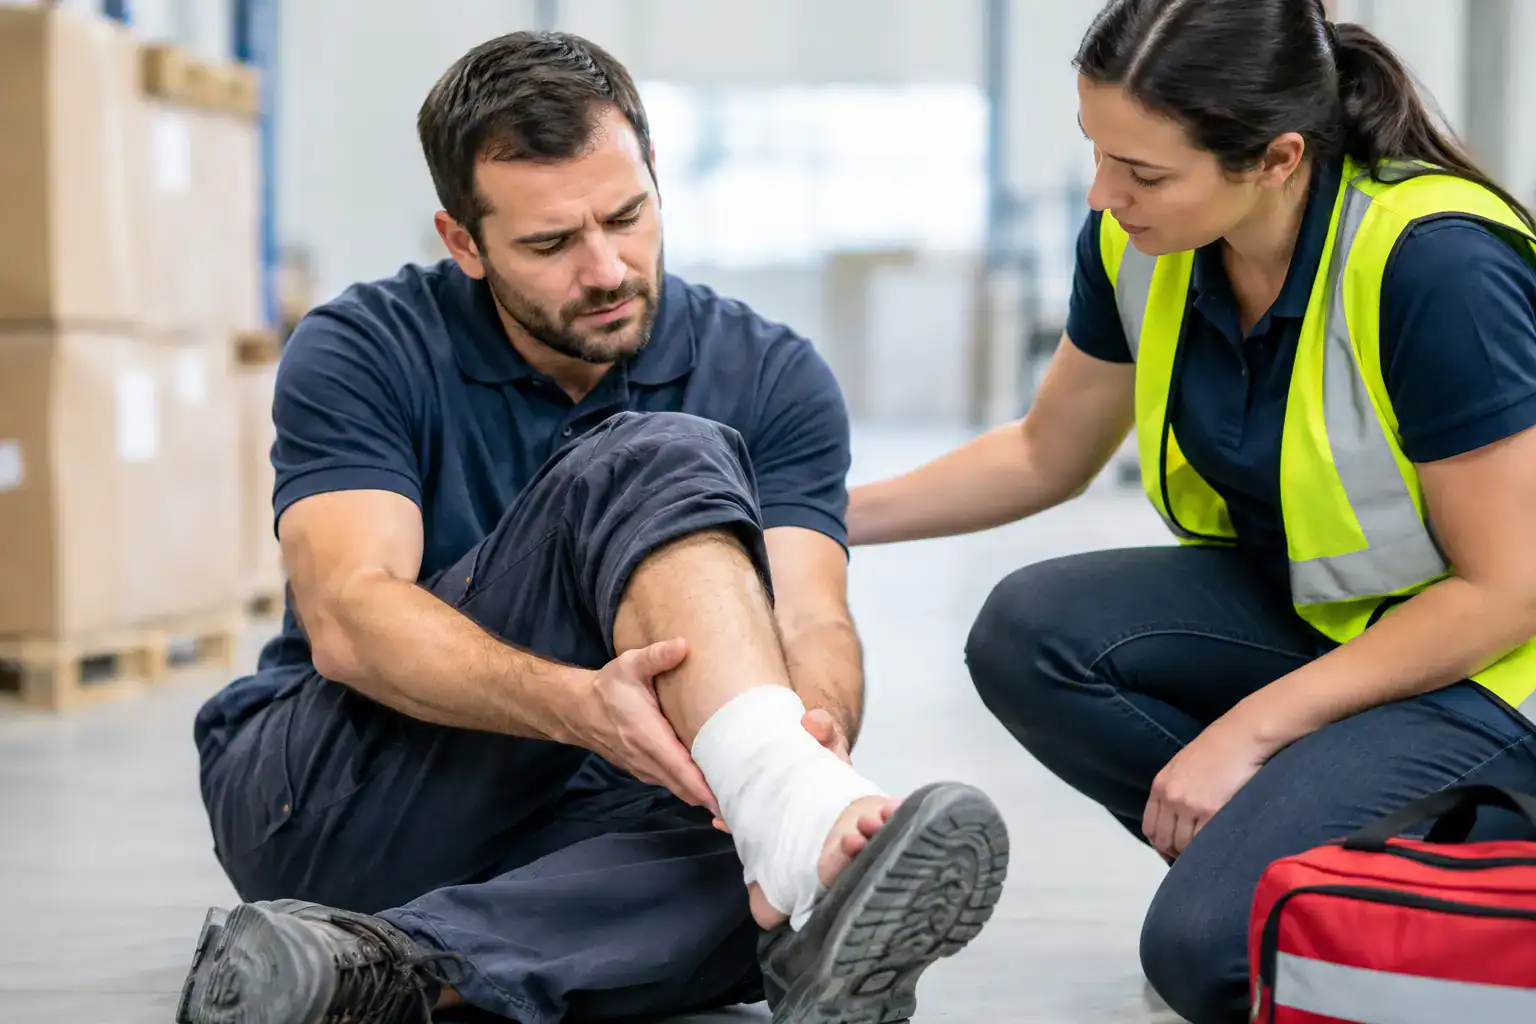
A crew member falls from a ladder. A restaurant employee burns a hand on a hot pan. An office worker develops a back injury after years at a desk. When an employee gets hurt, the business can face medical bills, lost-wage obligations, legal costs, and an abrupt operational problem. To cover employee injuries properly, most employers need workers’ compensation insurance – not general liability coverage.
For small-business owners, that distinction matters. Buying the wrong policy can leave a painful gap just when you expect insurance to respond. The right coverage can help protect your employees, your payroll, and the business you have worked to build.
What insurance covers employee injuries?
Workers’ compensation is designed for job-related injuries and illnesses. When a covered employee is hurt in the course of employment, the policy can generally pay for necessary medical care and a portion of lost wages while the employee recovers. It may also provide rehabilitation benefits and death benefits when a work injury is fatal.
In exchange, employees usually cannot sue their employer for ordinary workplace injuries. This arrangement is often called the workers’ compensation bargain. The employer provides no-fault benefits, and the employee generally receives those benefits without having to prove the employer caused the accident.
Most workers’ compensation policies also include employers liability coverage. This part can help with certain lawsuits that fall outside the usual workers’ compensation system, such as a claim brought by a third party connected to an employee’s injury. Limits, exclusions, and state rules apply, so it is not a replacement for careful workplace safety practices.
Why general liability is not enough
Commercial general liability insurance is essential for many businesses, but it serves a different purpose. It commonly helps cover third-party bodily injury, property damage, personal and advertising injury claims, and the cost to defend covered claims. For example, it may respond if a customer slips on a wet floor or if your employee damages a client’s property during a service call.
However, general liability policies generally exclude bodily injury claims made by your own employees when those injuries arise from their work. That exclusion exists because workers’ compensation is built to handle the employer-employee injury exposure. A contractor, retailer, consultant, or restaurant that carries only general liability may still have no coverage for a staff member’s workplace injury.
Is workers’ compensation required for your business?
In most states, employers with one or more employees are required to carry workers’ compensation. The specific rules vary by state, industry, payroll size, and the type of worker involved. Some states have different thresholds for domestic workers, agricultural labor, seasonal employees, officers, and family members. Texas has its own approach, allowing many private employers to opt out, although doing so can create significant lawsuit exposure and reporting requirements.
Do not assume a worker is exempt simply because they are part-time, paid hourly, paid in cash, or working temporarily. State agencies may treat that person as an employee based on the actual working relationship. Misclassifying an employee as an independent contractor can lead to premium audits, penalties, back payments, and uncovered claim risk.
Even where coverage is not legally required, a client, landlord, general contractor, licensing authority, or staffing agreement may require proof of workers’ compensation. Many businesses need a certificate of insurance before they can start a job, lease space, or win a contract.
What does workers’ compensation typically pay for?
A covered claim can involve more than an emergency room visit. Depending on the injury, state law, and policy terms, workers’ compensation may help pay for medical treatment, prescription medication, surgery, physical therapy, partial wage replacement, vocational rehabilitation, and permanent disability benefits.
Consider a small plumbing company. One technician injures a shoulder while moving equipment and cannot perform field work for several weeks. Medical expenses can add up quickly, while the employee may also be entitled to wage benefits. Without workers’ compensation, the owner could be paying those costs directly while trying to keep jobs staffed and customers served.
Coverage is not unlimited. Benefits are governed largely by state law, and disputes can arise over whether an injury was work-related, whether treatment is medically necessary, or when an employee can return to work. Intentional injuries, injuries caused while an employee is seriously violating policy, and incidents outside the scope of employment may not be covered. Each claim depends on its facts.
How to cover employee injuries with the right policy
Start with an accurate picture of your workforce. Insurers typically need your business location, industry, job duties, estimated annual payroll, number of employees, and prior claims history. A roofing company, for instance, has very different injury exposure than a bookkeeping firm, so payroll is classified by the work people actually perform.
Be specific about job duties. If an employee splits time between office administration and field installation, tell the insurance professional. Proper classification supports a more accurate premium and reduces the chance of unpleasant adjustments during an audit.
Next, select a workers’ compensation policy that meets your state’s requirements and any contract requirements. Some clients request particular employers liability limits or ask to be named on a certificate. A certificate confirms that coverage is in place, but it does not change policy terms or create coverage that the policy does not provide.
For many small businesses, workers’ compensation should sit alongside other core policies. General liability addresses injury claims from customers and other third parties. A business owner’s policy may combine general liability with commercial property coverage. Commercial auto can help with accidents involving business vehicles, while umbrella coverage can add liability limits above certain underlying policies. The right mix depends on how and where your business operates.
What affects the cost of workers’ compensation?
Workers’ compensation pricing is commonly based on payroll, employee job classifications, state rates, claims history, and the experience modifier that may apply to larger or more established employers. Higher-risk work usually costs more to insure because the chance and severity of injuries are greater.
A low premium should not be the only goal. Underreporting payroll or placing workers in an incorrect class may look cheaper upfront, but it can produce a large bill after a premium audit. It can also complicate a claim when you need support most. Give accurate estimates, then update your policy when you hire, add new services, open another location, or change the kind of work employees perform.
Safety can also affect long-term cost. Written procedures, safety training, protective equipment, maintained tools, and prompt incident reporting can reduce preventable injuries. A return-to-work plan can be just as practical. Modified duty may help an injured employee return safely sooner while helping the business manage disruption.
What to do after an employee is injured
Your first priority is the employee’s health. Get emergency medical care when needed, then follow your state’s rules and your insurer’s reporting instructions. Report the incident promptly, even if the injury initially seems minor. Delays can make a claim harder to investigate and may delay benefits for your employee.
Document basic facts while they are fresh: when and where the incident occurred, what work was being done, who saw it, and whether equipment or conditions may have contributed. Avoid making promises about benefits or deciding that a claim is not covered on your own. The insurance carrier and state workers’ compensation process will evaluate the claim.
Keep communication respectful and practical. An injured employee is often worried about treatment, income, and whether their job is secure. Clear communication can help the person navigate next steps and help you plan staffing needs without interfering with the claims process.
Get coverage before the next shift starts
Employee injuries are not limited to construction sites, warehouses, or delivery routes. A fall, repetitive-motion condition, lifting injury, or workplace accident can affect almost any small business. Workers’ compensation gives you a structured way to respond instead of paying potentially serious costs from operating cash.
If you are hiring your first employee, reviewing a contract, or unsure whether your current policy is enough, get a workers’ compensation quote and confirm the details for your state. GeneralLiabilityInsure.com can help you compare commercial coverage options and request proof of insurance when your business needs it. A policy in place before the next shift is one less business risk left to chance.
Related General Liability Insurance articles:
Free Business Insurance Quote
Want to speed up your quote? Call us at 855-767-7828